Building a productive, resilient biological economy across fourteen African countries
- Proposed aggregate development envelope: up to US$1.4 trillion
- Fourteen national programs: up to US$100 billion each, over approximately 25–30 years First launch countries: Morocco and Ghana
- Anchor economies: South Africa, Nigeria, Kenya and Zambia
- Core programs: Mauritius, Botswana, Namibia, The Gambia and Sierra Leone
- Conditional programs: Senegal, Madagascar and Equatorial Guinea, each subject to a country-specific entry protocol
Purpose of this proposal
Establish a coordinated continental platform that combines agricultural production, nine biotechnology platforms, processing, water, energy, logistics and workforce development. The objective is to turn locally available land, water and biological resources into dependable food supplies, commercially viable enterprises and durable employment, and to carry those gains to neighbouring countries through trade under the African Continental Free Trade Area (AfCFTA).
Decision requested
Approve development of the platform in principle; authorize country-level feasibility and negotiations; establish independent governance; and sponsor a funded project- preparation program. Construction and financing approvals remain project-specific.
Investment status
The US$1.4 trillion figure is a long-term mobilization and development target. It is not a representation that funds have been raised, committed or deposited. National participation, sponsor identity, investor commitments and individual project economics must be established through definitive documentation. All budgets, tiers and schedules in this proposal are proposed planning parameters, not claims of government acceptance.
Prepared for participating governments, institutional investors, development-finance partners, strategic operators and technology partners. October 2026.
1. Executive proposal
BioAfrica 1.4T proposes fourteen coordinated national development programs, each with an indicative envelope of up to US$100 billion. Agriculture and biological technology anchor the platform; enabling infrastructure makes production commercially usable.
National portfolios will be financially separated, while sharing research, training, procurement standards, technology qualification and market development.
Morocco and Ghana will launch first. South Africa, Nigeria, Kenya and Zambia join as anchor economies: they add market scale, capital-market depth and industrial capacity, and each enters under the conditions in section 9. Mauritius, Botswana, Namibia, The Gambia and Sierra Leone form the core portfolio. Senegal, Madagascar and Equatorial Guinea hold conditional places, each under its own protocol: public debt for Senegal, return to elected government for Madagascar, and integrity and counterparty screening for Equatorial Guinea. These designations are proposed roles, not claims of government acceptance.
Program at a glance
| Tier | Countries | Entry condition | Indicative envelope, US$bn |
| Launch | Morocco, Ghana | Readiness review and funded preparation | 200 |
| Anchor economies | South Africa, Nigeria, Kenya, Zambia | Country conditions in section 9 and site-level clearance | 400 |
| Core | Mauritius, Botswana, Namibia, The Gambia, Sierra Leone | Admission score, project pipeline and investor demand | 500 |
| Conditional | Senegal, Madagascar, Equatorial Guinea | Country protocol cleared before any negotiation or funding | 300 |
| Tier | Countries | Entry condition | Indicative envelope, US$bn |
| Total | 14 countries | 1,400 |
What the platform will build
Productive clusters: maize, rice, cassava, sorghum and legume systems, irrigation, biological inputs, horticulture, cocoa, cashew and coffee, livestock and feed, fisheries and aquaculture, and mushroom facilities linked to processing and buyers.
Biotechnology capacity: qualified strains and technologies, manufacturing, testing laboratories, traceability, technical support and locally validated application programs suited to humid, savanna, dryland and Mediterranean conditions.
Enabling systems: reliable water and energy, drought- and flood-resilient design, storage and cold chain, distribution, waste treatment, training and accessible finance for qualified local enterprises.
How it will be financed and managed
A continental sponsor and master developer will coordinate country programs and mobilize investors. Country vehicles and project companies will hold assets and financing separately. Revenue-producing projects will seek non-recourse or limited-recourse finance where bankable; public services and early research will require separately funded grants, concessional facilities or approved public support. No sovereign borrowing or guarantee arises merely from participation.
Scale and absorption
The envelope is large against every available benchmark, and the proposal treats it as a ceiling. US$1.4 trillion is about 93% of the fourteen countries’ combined 2026 GDP of roughly US$1.5 trillion, and fourteen times the US$100 billion that African Union members committed to mobilize for agrifood systems by 2035. Nine of the fourteen national envelopes exceed the host country’s annual GDP. Each envelope is therefore a reserved planning allocation over 25–30 years, drawn only as bankable projects close; section 5 sets out the comparison and section 13 the rules for reassigning capacity that a country cannot absorb.
Acceleration with investment discipline
This proposal front-loads preparation and viable deployment without promising immediate absorption of US$100 billion in any country. Multiple project packages may advance in parallel, but every construction draw requires verified land rights, permits, financing, safeguards and an executable delivery plan.
Expected results
The platform seeks stronger food security, lower post-harvest losses, more local processing, more intra-African trade, workforce skills, restoration of degraded land and better water and energy efficiency. Quantified employment, production, return and environmental targets will be established from baseline studies and approved feasibility models rather than assumed at continental scale.
2. Continental context and investment rationale
The fourteen countries combine five economies of more than US$100 billion each with nine smaller ones, across Mediterranean, Sahelian, humid, savanna, dryland and island farming systems. That mix makes a shared biological-economy platform more valuable than fourteen stand-alone programs: the large economies supply markets, capital and manufacturing, and the smaller ones supply stable operating bases and specialist production.
| Continental challenge | Why it matters | Platform response |
| Staple food gaps and price shocks | In Nigeria alone, about 34.7 million people were projected to face acute food insecurity in the June–August 2026 lean season (Nairametrics). | Raise domestic productivity, cut post-harvest losses and build reliable regional supply contracts. |
| Drought, flood and heat | Morocco has had five consecutive drought years (AgriFocus Africa). In Zambia, drought cuts hydropower and mining output as well as harvests (TimesLIVE). | Water-efficient irrigation, resilient siting and design, drought-adapted production, storage and independent power. |
| Continental challenge | Why it matters | Platform response |
| Costly inputs and degraded soils | Nigeria’s average NPK fertilizer price rose 19.5% in 2025, and the share of farmers using inputs fell from 81% to 62% (Nairametrics). | Qualified biological inputs, local blending, soil restoration and precision nutrition, validated before scale-up. |
| Post-harvest loss and thin cold chains | African Union members have committed to halve post-harvest losses by 2035 (Welthungerhilfe). | Drying, storage, cold chain and processing sited on verified crop volumes and buyer demand. |
| Livestock and aquaculture disease | South Africa’s 2026 foot-and- mouth outbreak affected more than 297,000 cattle and led China and Zambia to ban its meat exports (Africanews). | Veterinary laboratories, vaccine cold chains, biosecurity zoning and qualified probiotics. |
| Insecurity in farming areas | Conflict has displaced farmers and disrupted planting in northern Nigeria; Sahel violence continues to pull down the region’s peace scores (Ecofin Agency). | Site-level security clearance, modular assets, stop-work authority and no armed security from any party. |
| Sovereign debt limits | Senegal’s public debt is about 132% of GDP (Daba Finance); Kenya’s was 67.6% in January 2026 (Ecofin Agency); Zambia defaulted in 2020. | Project-level finance without sovereign borrowing or guarantees; debt review before any public contribution. |
| Uneven technical capacity | Laboratory, manufacturing and testing capacity is concentrated in a few economies. | Shared reference laboratories and training; technology transfer from South Africa, Morocco, Kenya and Mauritius. |
Continental policy already points the same way. The Kampala CAADP Declaration, adopted by the African Union in January 2025, commits members to raise agrifood output by 45%, halve post-harvest losses, triple intra-African agrifood trade and mobilize US$100 billion of public and private investment by 2035 (Welthungerhilfe). The 2024 Nairobi Declaration commits them to triple domestic fertilizer production and restore at least 30% of degraded soils by 2034 (Rural 21). All fourteen countries have ratified the AfCFTA agreement, which had 50 ratifications on 4 September 2026 (tralac). The platform will work within these frameworks rather than build parallel arrangements.
3. Country portfolio and continental integration
Each country gets a full national program; the specializations below identify where it can also serve the continent. The peace rank is each country’s global position among 163 states in the 2026 Global Peace Index.
| Country / entry | Peace rank | Proposed economic focus |
| Morocco / first launch | 65 | Fertilizer and biological-input manufacturing, water-efficient horticulture, olives and cereals, fisheries, export logistics to Europe and West Africa. |
| Ghana / first launch | 76 | Maize, rice and soybean productivity, cocoa, cashew and cassava processing, poultry feed, tilapia aquaculture, West African trade and training hub. |
| South Africa / anchor | 123 | Commercial grains, citrus and horticulture, livestock health, reference laboratories, biomanufacturing and co-investment capital. |
| Nigeria / anchor | 142 | Cassava, maize, rice and soybean value chains, poultry feed, catfish aquaculture, fertilizer blending, serving the continent’s largest consumer market. |
| Kenya / anchor | 132 | Export horticulture, tea, coffee and dairy, dryland livestock, seed systems, research partnerships and East African finance. |
| Zambia / anchor | 82 | Maize, soybean and wheat, beef and aquaculture, irrigation and independent power, supply to Southern and Central African markets. |
| Country / entry | Peace rank | Proposed economic focus |
| Mauritius / core | 18 | Finance and legal structuring, reference laboratories, blue economy, sugar-cane residue use and controlled-environment production. |
| Botswana / core | 50 | Beef and livestock health, veterinary laboratories, dryland and small-stock systems, water-efficient horticulture. |
| Namibia / core | 63 | Marine fisheries, beef, irrigated horticulture, desert controlled-environment farming and an Atlantic logistics corridor. |
| The Gambia / core | 56 | Rice, groundnuts and horticulture, river and coastal fisheries, small processing units sized to local markets. |
| Sierra Leone / core | 74 | Rice productivity, cocoa and oil-palm smallholders, fisheries, storage and community-level biological inputs. |
| Senegal / conditional | 75 | Rice, groundnuts, export horticulture and fisheries, financed without new sovereign borrowing. |
| Madagascar / conditional | 59 | Rice, vanilla and cloves, shrimp, soil restoration and cyclone-resilient storage, through eligible private and community counterparties until an elected government is in place. |
| Equatorial Guinea / conditional | 38 | Domestic food production, cocoa and fisheries, only after the integrity protocol is cleared. |
Selection basis
Ten countries are the ten highest-ranked African states in the 2026 Global Peace Index, at global ranks 18 to 76. The four anchor economies were added for scale rather than peace rank: Zambia stands at 82, South Africa at 123, Kenya at 132 and Nigeria at 142. Together the four hold about US$1.05 trillion of the fourteen countries’ US$1.5 trillion combined GDP, roughly 70%.
The peace index measures violence and militarization, not governance or integrity. Equatorial Guinea ranks second in Africa for peace and 172nd of 182 countries in the 2025 Corruption Perceptions Index. Admission therefore rests on the scoring framework in section 13, not on peace rank alone.
Complementary roles
Each country retains a complete national program, including all nine platforms where feasible. Specialization identifies opportunities for shared continental services; it does not require one country to depend on another for essential food, testing or operations. National business cases must remain viable if cross-border cooperation is delayed.
Mauritius is a small island economy with a limited farm sector. Its envelope is expected to be weighted toward finance, laboratories, the blue economy and outbound co-investment into the other thirteen programs.
Continental service hubs
| Hub function | Proposed lead hosts | Served markets |
| Fertilizer and biological-input manufacturing | Morocco, Nigeria, South Africa | All fourteen programs |
| Reference testing and product registration support | South Africa, Kenya, Morocco, Mauritius | All fourteen programs |
| Livestock health and veterinary vaccines | Botswana, Kenya, South Africa | Livestock programs |
| Seed systems and crop research | Kenya, Nigeria, Ghana, Zambia | Staple-crop programs |
| Fisheries and aquaculture genetics and hatcheries | Namibia, Ghana, Senegal, Madagascar | Coastal and inland-water programs |
| Finance, legal structuring and treasury | Mauritius, South Africa, Morocco, Kenya | All fourteen programs |
| Training academy and extension curriculum | Ghana, Kenya, South Africa, Morocco | All fourteen programs, in English and French |
| Port and corridor logistics | Morocco, Ghana, Kenya, Namibia, South Africa | Coastal and landlocked programs |
Hub designation is a planning proposal. Each hub must be commercially viable on its own demand and earns no exclusive supply rights.
Trade and supply-chain design
All fourteen countries have ratified the AfCFTA agreement (tralac). Ratification does not by itself deliver duty-free access: preferences apply only where both trading partners have implemented tariff schedules and rules of origin are settled for the product. Each corridor must be verified before export revenues enter a financing base case.
The programs also sit in overlapping regional blocs: ECOWAS for Ghana, Nigeria, Senegal, The Gambia and Sierra Leone; SADC for South Africa, Botswana, Namibia, Zambia, Mauritius and Madagascar; the East African Community for Kenya; and the Central African bloc for Equatorial Guinea. Regional arrangements will cover product qualification, lawful movement of biological materials, phytosanitary requirements, origin rules, food safety, halal certification where relevant, customs documentation and cold- chain integrity.
Access to the United States under AGOA is extended only to 31 December 2026, and a 30% United States tariff applies to certain South African goods (Baker McKenzie). Base cases will not assume AGOA preferences beyond that date. European buyers of cocoa, coffee, oil palm and cattle products will require deforestation-free traceability.
Country admission
Admission requires authorized government counterparts, legal and tax review, security and resource assessments, a national project pipeline, environmental and social screening, transparent procurement arrangements and an agreed governance score.
Founding status gives no automatic entitlement to financing.
Reserve-country readiness
Tunisia, Angola and Malawi, the next-ranked states in the peace index, Côte d’Ivoire and Tanzania further down it, and Seychelles and Cabo Verde, first and third in the 2024 Ibrahim Index ofAfrican Governance, may be evaluated as reserve hosts, with Rwanda and Egypt considered for specific functions. Replacement is based on economic function and verified capacity. Reserve participation does not add another US$100 billion to the US$1.4 trillion target without an explicit portfolio amendment.
4. Nine biotechnology platforms
| Platform | Proposed applications and commercial outputs | Early priority countries |
| 1. Agricultural Biotechnology | Qualified microbial inputs, legume inoculants, maize, rice, cassava and vegetable seed and nursery services, diagnostics and locally tested agronomic programs. | Ghana, Nigeria, Kenya, Zambia |
| 2. Controlled Environment Agriculture | Greenhouses, net houses, nurseries and vertical farms sized to energy, water, heat load and buyer requirements. | Morocco, South Africa, Mauritius, Namibia |
| 3. Precision Nano Nutrition | Analytical services and precision nutrient delivery; nano-enabled products require characterization and safety review before use. | Morocco, South Africa, Mauritius |
| 4. Living Rhizosphere Technology | Root-zone management, microbial inoculation, mycorrhizal programs, acid and phosphorus- fixing soil diagnostics, dryland restoration and field extension. | Zambia, Nigeria, Senegal, Madagascar |
| 5. Biological Crop Protection | Registered biological pest and disease products for maize, horticulture, citrus, cocoa and cashew, monitoring and integrated pest management. | Kenya, South Africa, Ghana, Morocco |
| 6. Aquaculture Biotechnology | Tilapia, catfish and shrimp hatcheries, water-quality management, feed technologies, biosecurity and marine-catch processing. | Ghana, Nigeria, Namibia, Madagascar |
| Platform | Proposed applications and commercial outputs | Early priority countries |
| 7. Animal Health & Probiotics | Qualified feed and probiotic products, veterinary oversight, vaccine cold chains, cattle, small- stock and poultry biosecurity, herd monitoring and manure management. | Botswana, Namibia, Kenya, South Africa |
| 8. Environmental Biotechnology | Wastewater bioaugmentation where validated, treatment of cocoa, cassava, sugar-cane and abattoir residues, composting and restoration. | South Africa, Morocco, Mauritius, Ghana |
| 9. Mushroom Biotechnology | Spawn laboratories, edible and specialty mushroom production, substrate preparation from crop residues and spent-substrate reuse. | Sierra Leone, The Gambia, Kenya, Zambia |
One integrated operating system
Maize stover, rice husks, cassava peel, cocoa pod husk and sugar-cane bagasse may supply approved mushroom substrates, composting or energy projects instead of open burning or dumping. Treated water may support permitted reuse after fit-for-purpose verification. Shared laboratories will serve manufacturing and field operations. Every material transfer requires specifications and testing; biological treatment alone does not establish that water or residues are safe for reuse.
Technology qualification
MicrobeBio may be evaluated as a biological technology partner under a disclosed commercial agreement, alongside African suppliers and national research institutes. Product selection will depend on independent trials, national registration, quality, capacity and competitive terms. Sponsor-affiliated suppliers must disclose ownership and undergo the same qualification and conflict controls as other vendors.
Biological input specifications will distinguish CFU, spores and mycorrhizal propagules; require identity, purity, viable counts, shelf-life evidence under hot, unrefrigerated storage and batch traceability; and define storage and delivery conditions. No universal yield increase, fertilizer reduction or pest-control outcome is assumed. Nano-enabled nutrition will advance only after exposure, residue, worker-safety and environmental review. No genetically modified organism is assumed; any such product needs approval from the national biosafety authority. Movement of strains across borders will respect national biosafety rules and access-and-benefit-sharing obligations.
Product registration pathway
Each biological product follows four steps before commercial scale: laboratory characterization; multi-site, multi-season field or pond trials with untreated controls; national registration in each country of sale; and post-registration monitoring of performance and complaints. Registration in one country does not authorize sale in another.
5. National investment architecture
The reference allocation below prioritizes production and biotechnology while reserving substantial capacity for the infrastructure that makes them operable. Against the BioAsia 900 baseline it shifts weight from aquaculture toward livestock, soil restoration, processing and utilities, reflecting African farming systems and infrastructure gaps. It is a portfolio-design baseline, not a project cost estimate; country allocations may change after feasibility and investment approval.
| Use of funds | Per country, US$bn | Fourteen-country total, US$bn |
| Agriculture, irrigation and farm infrastructure | 24 | 336 |
| Controlled environment agriculture | 5 | 70 |
| Precision nutrition and application systems | 3 | 42 |
| Living rhizosphere and soil restoration | 6 | 84 |
| Biological crop protection | 4 | 56 |
| Aquaculture and fisheries value chains | 6 | 84 |
| Use of funds | Per country, US$bn | Fourteen-country total, US$bn |
| Animal health, probiotics and livestock | 9 | 126 |
| Environmental biotechnology and waste systems | 5 | 70 |
| Mushroom production and biotechnology | 2 | 28 |
| Food processing, storage and logistics | 12 | 168 |
| Shared energy, water and digital utilities | 12 | 168 |
| Research, laboratories and workforce | 5 | 70 |
| Development costs, startup liquidity and contingency | 7 | 98 |
| TOTAL | 100 | 1,400 |
Envelope against each economy
Equal US$100 billion envelopes fit the fourteen economies very differently. Spread over 30 years, an envelope averages US$3.3 billion a year: under 1% of South Africa’s GDP, and more than the entire annual output of The Gambia. GDP figures are IMF 2026 estimates.
| Country | GDP 2026, US$bn | Envelope as a multiple of annual GDP |
| South Africa | 480.0 | 0.2 |
| Nigeria | 377.4 | 0.3 |
| Morocco | 194.3 | 0.5 |
| Kenya | 147.3 | 0.7 |
| Ghana | 118.3 | 0.8 |
| Zambia | 41.2 | 2.4 |
| Senegal | 40.5 | 2.5 |
| Botswana | 21.9 | 4.6 |
| Madagascar | 21.2 | 4.7 |
| Country | GDP 2026, US$bn | Envelope as a multiple of annual GDP |
| Namibia | 17.3 | 5.8 |
| Mauritius | 17.1 | 5.8 |
| Equatorial Guinea | 13.7 | 7.3 |
| Sierra Leone | 8.3 | 12.1 |
| The Gambia | 2.8 | 35.8 |
| Fourteen countries | 1,501.3 | 0.9 |
Three working rules follow. First, every envelope is a ceiling on a reserved planning allocation; drawdown follows bankable projects, not the envelope. Second, a smaller economy may host assets that serve regional demand, but the business case must name the buyers and the trade route. Third, at each five-year review, capacity without a qualified pipeline may be reassigned under the section 13 rules, so that the nine smaller programs are not measured against a figure they were never expected to absorb.
Country weighting
The reference allocation is a starting point. Each national program will rebalance within its US$100 billion envelope after feasibility. Expected directions: Morocco, South Africa and Mauritius toward controlled-environment agriculture, laboratories and manufacturing; Botswana, Namibia, Kenya and Zambia toward livestock, irrigation and utilities; Ghana, Nigeria, Senegal, The Gambia and Sierra Leone toward staple crops, processing and aquaculture; Madagascar toward rice, soil restoration and storage. Rebalancing beyond 25% of any line requires Investment Committee approval.
Cost and accounting discipline
The agriculture line covers field production and farm irrigation; the rhizosphere line covers biological services and restoration, avoiding duplicate farm capital costs. Shared utilities are budgeted once at the asset owner. Each project estimate must include engineering, equipment, land access, construction, duties, financing costs, commissioning, startup working capital and contingency, plus drought, flood and cyclone design allowances where relevant.
The US$1.4 trillion total measures eligible development expenditures funded across all sources. Guarantees and insurance are reported separately as credit support.
Refinancing existing expenditure is not counted as new development. Reinvested cash counts only when it funds new eligible expenditure; neither dividends nor loan repayments increase the target.
Capital status ledger
Reports will separately identify pipeline value, approved project budgets, binding commitments, financial close, available drawdowns and actual disbursement. A reserved national envelope is an unfunded planning allocation unless supported by documented financing. Continental totals must reconcile to country and project ledgers.
6. Capital mobilization and investor economics
Proposed source mix
| Source | Illustrative share | National / continental, US$bn |
| Sponsor and strategic equity | 20% | 20 / 280 |
| Institutional growth and infrastructure equity | 15% | 15 / 210 |
| Commercial and development-finance debt | 45% | 45 / 630 |
| Concessional debt | 15% | 15 / 210 |
| Grants and expressly approved public contributions | 5% | 5 / 70 |
| TOTAL | 100% | 100 / 1,400 |
This mix is a mobilization scenario, not evidence of investor participation. Equity-heavy research ventures, concessional food-security programs and leveraged utility projects will require different structures. The mix will differ by country: South Africa, Morocco and Mauritius are expected to lean toward commercial equity, debt and domestic institutional capital; Ghana, Kenya, Zambia and Senegal will need project-level and concessional finance that adds no sovereign debt; The Gambia, Sierra Leone and Madagascar will need
a larger grant and concessional share; and Nigerian packages will favour naira funding to limit currency exposure. Land or other in-kind contributions will count only at independently verified eligible value; they are not cash available for drawdown.
Potential capital channels
Outreach may target the African Development Bank, Afreximbank, the Africa Finance Corporation, the International Finance Corporation and bilateral development-finance institutions; sovereign wealth funds; African pension and insurance funds, notably in South Africa, Nigeria, Kenya, Namibia and Botswana; strategic fertilizer, agribusiness and food companies; commercial lenders; export-credit agencies; equipment financiers; diaspora investors; Islamic-finance providers where sukuk-eligible assets exist; and qualified climate-finance providers. Institutions are prospective counterparties only.
Investor mandates, currency, tenor, country exposure and safeguards must fit the underlying projects.
Most project revenues will be earned in local currency. Hard-currency debt will be sized only to contracted hard-currency revenues; the rest will seek local-currency funding from domestic banks, pension funds and development lenders.
Investment vehicles
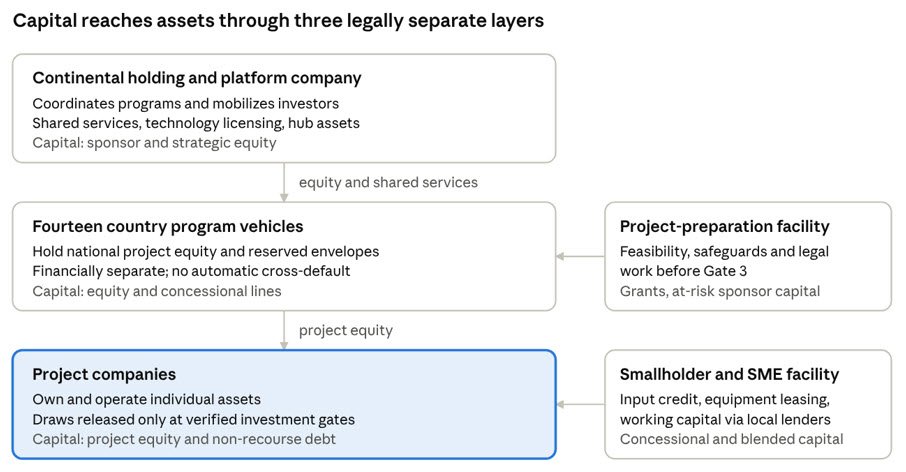
investment vehicles · 3 layers, 2 facilities
Each layer keeps its own assets, debt and accounts, so a failure in one project or country does not pass to another. The preparation facility pays for work before financial close, and the smallholder facility reaches farmers and suppliers through local lenders rather than direct lending.
Revenue and return generation
Commercial revenues may include grains and horticulture, cocoa, cashew and coffee products, meat and dairy, fish, mushrooms, registered biological inputs and blended fertilizer, processing and drying services, storage, distribution, laboratory testing and contracted utility services. Public-benefit projects need identifiable grant or budget funding where user charges cannot cover costs. Carbon revenues, including from soil carbon, avoided burning or rangeland management, will be excluded from the base case until methodology, tenure, additionality, host-country authorization and buyer eligibility are verified.
Project underwriting requirements
Each investment memorandum will contain a full construction-to-exit financial model: capacity, ramp-up, realistic sales prices, rejection and mortality allowances, operating costs, maintenance, taxes, working capital, debt service, replacement capital and residual value. It will report unlevered returns, equity returns, NPV, debt coverage, break-even volumes and covenant headroom. Required returns and coverage ratios will be negotiated by asset class; no continental return is guaranteed.
Downside tests and distributions
Models must test delayed completion, higher capital costs, lower yields or occupancy, lower sales prices, higher input and energy costs, currency devaluation and transfer delays, drought and flood losses, power and port interruptions, disease outbreaks in livestock and aquaculture, security-related stoppages, and combined downside conditions. Debt will be sized to the approved downside case. Cash distributions follow documented priorities for essential operations, taxes, debt service, reserves and approved shareholder payments, with lockups when covenants fail.
7. Accelerated deployment strategy
Speed will come from concurrent preparation, repeatable designs, qualified operators and existing assets that can be upgraded. A continental announcement will not substitute for financial close. The national schedule below is a stretch planning scenario to be reset after the first readiness review.
Reference national schedule
| Period after national launch | Incremental US$bn | Cumulative US$bn | Primary deployment |
| Year 1 | 0.5 | 0.5 | Studies, approved demonstrations, rehabilitation and initial operating support. |
| Years 2–3 | 4.5 | 5 | First financeable production clusters and essential utility packages. |
| Years 4–5 | 10 | 15 | Repeat proven modules, expand processing and biological manufacturing. |
| Years 6–10 | 25 | 40 | Larger corridors, regional supply chains and proven industrial assets. |
| Years 11–20 | 35 | 75 | Portfolio expansion, new capacity and modernization. |
| Years 21–30 | 25 | 100 | Remaining approved investments and replacement or expansion assets. |
This schedule applies to each country separately and starts its own clock at national launch. It is not an aggregate ten-year US$1.4 trillion commitment. It is a ceiling path for the five largest economies and will not be reached in the smaller ones, where section 5 applies. Faster deployment is permitted when verified project readiness and financing justify it; missed readiness milestones reduce disbursement rather than weaken safeguards.
Continental entry sequence
| Tier | Countries | Preparation starts | Earliest national launch |
| Launch | Morocco, Ghana | Program year 1 | Program year 1 |
| Anchor economies | South Africa, Zambia | Program year 1 | Program years 1–2, after counterpart and site confirmation |
| Anchor economies | Nigeria, Kenya | Program year 1 | Program year 2, after the 2027 elections confirm counterparts |
| Core | Mauritius, Botswana, Namibia | Program years 1–2 | Program years 2–3, by admission score and pipeline |
| Core | The Gambia, Sierra Leone | Program years 1–2 | Program years 2–4, at a scale set by absorption review |
| Conditional | Senegal | Program year 1 | After protocol clearance, targeted for program year 2 |
| Conditional | Madagascar | Program year 1, legal and eligibility review only | Only after an elected government is in place; no date before 2028 |
| Conditional | Equatorial Guinea | Program year 1, integrity review only | Only when the integrity protocol is cleared; no target date |
Three electoral calendars shape the first eighteen months. The Gambia votes for president on 5 December 2026. Nigeria holds presidential and National Assembly elections on 16 January 2027 and state elections on 6 February 2027. Kenya votes in 2027. No definitive agreement will be scheduled for signature in the ninety days before a national election.
Investment gates
Gate 1: eligibility, authorized counterparties, preliminary security and legal clearance, sanctions and integrity screening and an approved preparation budget.
Gate 2: site options, resource testing, commercial concept, safeguard scoping and operator capability.
Gate 3: bankable feasibility, confirmed land rights, required permits, buyer evidence, executable contracts and financial close.
Gate 4: independent engineering certification, controlled payments and construction milestones.
Gate 5: commissioned assets, demonstrated operating performance and authorization for replication.
Parallel delivery lanes
Advance farm and irrigation rehabilitation, biological field trials across at least two seasons, buyer negotiations, site due diligence and utility studies concurrently. Use modular plants and standardized procurement specifications after testing. Schedule construction around each region’s rainy season. Early procurement of long-lead equipment requires approved cancellation exposure and storage arrangements.
Expansion of unproven biology or unregistered products remains outside the accelerated lane.
8. Launch programs: Morocco and Ghana
Morocco and Ghana launch first because each pairs a stable operating base with a distinct continental role: Morocco as the manufacturing and export hub for fertilizer and biological inputs, Ghana as the production, processing and training hub for West Africa. No location in either country is presumed ready before assessment.
Morocco
The Morocco program will develop its own production and biotechnology portfolio while serving as the platform’s input-manufacturing hub. Morocco holds about 70% of the world’s phosphate reserves, which makes it the natural host for blended mineral and biological nutrition products. Packages will align with the government’s Generation Green strategy for 2020–2030, now under mid-term review, rather than duplicate it. After five consecutive drought years, every production package must show a secured, sustainable water source before Gate 3.
| Region | Candidate clusters for screening |
| Casablanca–Settat and the Jorf Lasfar corridor | Biological-input and fertilizer formulation, reference laboratories, export logistics. |
| Souss-Massa | Export horticulture and citrus, protected cultivation, desalinated and reused water, fisheries processing. |
| Gharb and Loukkos | Irrigated field crops, sugar crops, berries and rice, biological crop protection. |
| Fès-Meknès and the Saïss plain | Olives, cereals and pulses, soil-health programs, agro-processing. |
| Oriental and pre-Saharan oases | Date palm, small-stock systems, water- efficient irrigation and mushroom units. |
Any site in Western Sahara requires separate legal review before screening, because the territory’s status is disputed and trade preferences may not apply to its products.
| Illustrative first-year package | US$ million |
| Legal, feasibility, water-resource and safeguard studies | 35 |
| Biological-input and fertilizer formulation plants and laboratories | 120 |
| Water-efficient irrigation, desalinated and reused water supply | 110 |
| Horticulture, olive and cereal production clusters | 80 |
| Fisheries, aquaculture and cold chain | 60 |
| Processing and export logistics | 50 |
| Training and digital traceability | 20 |
| Startup liquidity and contingency | 25 |
| Illustrative first-year package | US$ million |
| TOTAL | 500 |
Ghana
Ghana will be the first sub-Saharan development priority, with maize, rice, soybean, cocoa, cashew, cassava, poultry and aquaculture supported by essential water, power, storage, processing and workforce systems. The macroeconomic base has improved: Ghana completed its US$3 billion IMF programme in July 2026, inflation stood at 5.3% in June 2026, and its risk of debt distress was upgraded to moderate (Ghana News Agency). The program will still add no sovereign borrowing or guarantee.
| Zone | Candidate clusters for screening |
| Northern savanna | Maize, rice, soybean and groundnut farms, small- scale irrigation, shea and cashew collection, drying and storage. |
| Middle belt | Cassava and cashew processing, poultry and feed, maize, mushroom units and biological-input supply. |
| Forest belt | Cocoa rehabilitation and traceability, oil palm, cocoa-husk composting and biological crop protection. |
| Volta Lake and the coast | Tilapia hatcheries and cage culture, feed, cold chain and fish processing. |
| Greater Accra and Tema | Formulation and packaging, reference laboratory, national training academy and export logistics. |
| Illustrative first-year package | US$ million |
| Legal, feasibility, resource and safeguard studies | 40 |
| Maize, rice and soybean farm and irrigation rehabilitation | 130 |
| Cocoa, cashew and cassava processing | 90 |
| Poultry feed, hatcheries and tilapia aquaculture | 70 |
| Illustrative first-year package | US$ million |
| Storage, cold chain and port logistics | 60 |
| Water, power and access infrastructure | 50 |
| Training, extension and laboratories | 30 |
| Startup working capital and contingency | 30 |
| TOTAL | 500 |
Each US$500 million budget sits inside the national US$100 billion envelope and the reference allocation, and requires its own funding commitments, independent costing and package-level approvals. If land access, protection of workers or public-service capacity cannot be secured, the spending plan will narrow to lawful preparation and safe, viable projects.
Community and operating arrangements
Farmers may participate through voluntary supply agreements, service contracts, cooperatives or joint ventures. Terms will disclose prices, deductions, input finance and dispute procedures. In Ghana, most farmland is held under customary tenure by stools, skins and families; in Morocco, collective lands and water rights carry their own rules.
Community consultation, documented consent where required by law, registered leases and livelihood protection will precede any land acquisition. Local enterprises will receive supplier-development support. Private program personnel will not exercise police or sovereign authority.
Morocco–Ghana cooperation
The two launch countries may share training, product testing, technical support and approved supply arrangements, in French and English. Moroccan manufacturing may supply Ghanaian projects only where access, cost and continuity are demonstrably reliable; essential Ghanaian operations must maintain alternative suppliers. Each transaction requires separate customs, phytosanitary, payment and product-compliance review.
Replication decision
Independent reviews will measure water reliability, marketable production, post-harvest loss, farmer economics, buyer payment, operating continuity through drought and flood, quality and safeguard performance. Demonstrations will use suitable controls and comparisons across at least two seasons. Scale only packages with credible operating evidence and a funded expansion plan.
9. Anchor-economy programs: South Africa, Nigeria, Kenya and Zambia
The four anchor economies bring the scale the stability-ranked ten lack: about 70% of the portfolio’s GDP, its deepest capital markets and most of its manufacturing and laboratory capacity. They also carry its hardest operating risks, so each enters under stated conditions.
| Country | Lead packages | Continental contribution | Key conditions |
| South Africa | Grains, citrus and horticulture, livestock health, biomanufacturing, reference laboratories | Testing, registration support, engineering and co-investment capital | Contracted power and logistics alternatives; land-claim verification; livestock disease controls |
| Nigeria | Cassava, maize, rice and soybean, poultry feed, catfish aquaculture, fertilizer blending | Largest consumer market; input manufacturing for West Africa | Site-level security clearance; currency and repatriation terms; state-level land rights |
| Kenya | Export horticulture, tea, coffee, dairy, dryland livestock, seed systems | Research partnerships, East African finance and logistics | No sovereign borrowing or guarantees; county and community land consent |
| Country | Lead packages | Continental contribution | Key conditions |
| Zambia | Maize, soybean, wheat, beef, aquaculture, irrigation | Grain and protein supply to Southern and Central Africa | No sovereign borrowing or guarantees; drought- proof water and power |
South Africa
South Africa’s program builds on the continent’s most developed commercial farming, laboratory and capital-market base. Priorities are biomanufacturing and formulation, a continental reference laboratory, citrus and horticulture export systems, grain and oilseed productivity, and livestock health. Jobs matter as much as output: unemployment stands at 32% (Engineering News).
Three conditions apply. Load-shedding has ended and rail and ports have improved, but a July 2026 reform tracker reported reversals in electricity reform and delays in separating rail infrastructure from Transnet, so export packages need contracted power and logistics alternatives. The foot-and-mouth outbreak was declared a national disaster, with a target to vaccinate 80% of the national herd by December 2026 (Africanews); livestock packages will wait for zone-level disease status. Every site needs verification of title, restitution claims and labour-tenant rights.
Nigeria
Nigeria is the portfolio’s largest consumer market and its least peaceful country, ranked 142nd of 163. Priorities are cassava, maize, rice and soybean value chains, poultry feed, catfish aquaculture, fertilizer blending and storage, placed first in states where access is verified.
No site proceeds without an independent security assessment, and no package relies on armed protection from any party. Conflict in the north has displaced farmers and disrupted planting (Nairametrics). Financing will favour naira funding, with documented conversion and repatriation arrangements for any foreign capital. Land is held through state governments, so each package needs state-level rights and community consent.
National elections fall on 16 January and 6 February 2027; counterparts will be reconfirmed afterward.
Kenya
Kenya’s program centres on export horticulture, tea, coffee and dairy, dryland livestock systems, seed and research partnerships, and Nairobi’s role as East Africa’s financial centre. Biological crop protection has a ready market in export horticulture, where buyers set strict residue limits.
Public debt was 12.4 trillion shillings, or 67.6% of GDP, at the end of January 2026, and Kenya had no IMF programme after the previous one was abandoned in March 2025; talks on a new one were continuing in May 2026 (Ecofin Agency). No Kenya package may create sovereign borrowing, guarantees or contingent liabilities. Agriculture is a county function, so county governments and community land holders must be parties to site agreements. Counterparts will be reconfirmed after the 2027 election.
Zambia
Zambia offers land, water and a central position between Southern, East and Central African markets. Priorities are maize, soybean and wheat, beef, aquaculture, irrigation and storage, with grain and protein supply to neighbouring deficit markets.
Political continuity is established: President Hakainde Hichilema was re-elected with about 60% of the vote in August 2026. Fiscal space is not. Zambia defaulted in 2020, its US$1.7 billion IMF arrangement expired in January 2026, and the government is seeking a new programme while staying out of international bond markets (TimesLIVE). No Zambia package may create sovereign borrowing or guarantees. Because drought cuts hydropower as well as harvests, every package must carry its own irrigation and independent power case. Conversion of customary land requires documented consent from chiefs and affected households.
Anchor-economy financial structure
The four programs will use separate project companies, independent custody, milestone payments and documented currency arrangements. Their size does not entitle them to faster disbursement: the same gates apply, and no anchor program may create a cross- default for another national program.
10. Core programs: Mauritius, Botswana, Namibia, The Gambia and Sierra Leone
The five core countries are among Africa’s most peaceful and offer dependable operating bases. All five are small economies, so their programs are sized to verified pipelines and regional demand, and each enters when its admission score, project pipeline and investor demand support launch, targeted for program years 2–4.
| Country | Lead packages | Continental contribution | Key conditions |
| Mauritius | Reference laboratories, blue economy, sugar- cane residue use, controlled- environment production | Finance, legal structuring and treasury hub; outbound co- investment | Commercial capital only; land and freshwater limits |
| Botswana | Beef and small stock, veterinary laboratories, dryland and water- efficient horticulture | Livestock health and vaccine services | No public funding assumed; water availability; disease- free zoning |
| Namibia | Marine fisheries processing, beef, irrigated horticulture, desert controlled- environment farming | Atlantic logistics corridor for landlocked neighbours | Sustainable catch limits; river-basin water allocation |
| The Gambia | Rice, groundnuts, horticulture, river and coastal fisheries | Demonstration site for small-economy modules | Scale set by absorption review; counterparts reconfirmed after the December 2026 election |
| Sierra Leone | Rice, cocoa and oil- palm smallholders, fisheries, storage | Smallholder and community delivery models for humid West Africa | Customary land consent; grant and concessional share; no forest conversion |
Mauritius
Mauritius is Africa’s most peaceful country for the nineteenth year running and ranked second in the 2024 Ibrahim Index of African Governance. Its program is weighted toward services: a finance, legal and treasury hub for the platform, a reference laboratory, blue- economy and aquaculture ventures, sugar-cane residue valorization and controlled- environment vegetables for a food-importing island. Mauritian vehicles may hold and channel investment into the other thirteen programs, priced at arm’s length and fully disclosed.
Botswana
Botswana’s program centres on beef and small-stock value chains, veterinary laboratories and vaccine services for the region, and water-efficient horticulture. No Botswana public funding is assumed: Moody’s cut the sovereign rating to Baa2 in September 2026, its second downgrade in under a year, citing weaker diamond revenue (Mining Weekly).
Diversification into agriculture fits that pressure, but packages must stand on commercial and development finance. Groundwater and river allocations will be verified before any irrigation commitment.
Namibia
Namibia’s program builds on marine fisheries, beef exports and irrigated horticulture along its perennial border rivers, with controlled-environment farming where energy and water costs allow. The Atlantic port and corridor system can serve Botswana, Zambia and other landlocked markets. Fisheries packages will invest in processing and cold chain within scientifically set catch limits, not in additional fishing effort.
The Gambia
The Gambia is the portfolio’s smallest economy, at about US$2.8 billion, so its envelope is almost entirely reserved capacity. The program will begin with modest, replicable packages: rice productivity in the river valley, groundnut quality and processing, horticulture, and river and coastal fisheries with cold storage. It will serve as the platform’s test of small-economy modules before they are repeated elsewhere. The presidential election is set for 5 December 2026; preparation continues, and counterparts will be reconfirmed afterward.
Sierra Leone
Sierra Leone’s program targets rice productivity and storage, cocoa and oil-palm smallholder rehabilitation, fisheries and community-level biological inputs. It ranks 109th of 182 in the 2025 Corruption Perceptions Index, so independent custody of funds and third-party procurement apply from the first dollar. Land is held under customary tenure; packages need documented consent from landholding families and no conversion of primary forest.
Core-program financial structure
Core programs will open with grant-funded and concessional preparation, then seek commercial capital package by package. First-year preparation budgets are proposed at US$100 million each for Mauritius, Botswana and Namibia and US$50 million each for The Gambia and Sierra Leone, subject to funding commitments.
11. Conditional programs: Senegal, Madagascar and Equatorial Guinea
The three conditional countries rank among Africa’s ten most peaceful and hold full US$100 billion envelopes, but each carries a specific risk that peace rank does not capture. Each enters only after clearing a country-specific protocol. Until then, spending is limited to legal review, feasibility and eligible preparation.
| Country | Protocol conditions before negotiation or funding | Illustrative first-year preparation budget, US$ million |
| Senegal | IMF programme approved and debt treatment defined; no sovereign borrowing, guarantees or state- enterprise contingent liabilities. | 150 |
| Madagascar | Elected government in place and African Union suspension lifted for full entry; until then, counsel- cleared dealings with eligible private and community counterparties only. | 50, grant-funded only |
| Country | Protocol conditions before negotiation or funding | Illustrative first-year preparation budget, US$ million |
| Equatorial Guinea | Independent integrity review; beneficial-ownership disclosure for every counterparty; independent custody and procurement. | 25, review only |
Senegal
Senegal’s public-sector debt reached about 132% of GDP at the end of 2024 after more than US$11 billion of previously misreported borrowing came to light. The IMF reached a staff-level agreement on a US$2.2 billion, three-year programme in September 2026 that still needs Executive Board approval, and Senegal’s international bonds traded below 50 cents on the dollar (Daba Finance).
No Senegal package may create sovereign borrowing, guarantees or contingent liabilities for state-owned enterprises; financing must be project-level, grant or concessional. No package passes Gate 3 until the IMF programme is approved and the treatment of existing creditors is known, because both determine tax, currency and public- contribution assumptions. Priority packages are irrigated rice in the Senegal River valley, groundnut processing, export horticulture and fisheries cold chain.
Madagascar
Madagascar is included for its food-security need and its rice, vanilla, clove and shrimp potential. It is also the portfolio’s least settled jurisdiction. The military took power in October 2025 after weeks of protests; the African Union suspended Madagascar; and the transition roadmap of February 2026 plans presidential elections in 2027 (ISS Africa).
Participation follows a strict protocol:
- Counterparty Counsel must clear every transaction, counterparty and beneficial owner before negotiation and again at each material step. No long-term concession, land right or public commitment will be signed with transitional authorities.
- Delivery model. Small, modular, low-capital packages delivered through eligible private firms, cooperatives, NGOs and community organizations, starting with grant-funded seed, storage, soil-restoration and biological-input
- Full-entry trigger. Commercial debt and equity deploy only after an elected government takes office, the African Union lifts its suspension, and the Investment Committee and financing parties confirm
- Climate Cyclone-resilient design and storage are mandatory for every asset.
- If the transition timetable slips, the envelope stays reserved and uncommitted capacity may be reassigned under section 13.
Equatorial Guinea
Equatorial Guinea ranks second in Africa and 38th in the world for peace, but 172nd of 182 countries in the 2025 Corruption Perceptions Index. Stability alone does not make it investable. Its program begins with an independent integrity review, and nothing else proceeds until the review is accepted by the Audit and Compliance Office and the Investment Committee. The protocol requires:
- Ownership transparency. Beneficial-ownership disclosure and enhanced screening of politically exposed persons for every counterparty, contractor and
- Independent money handling. Funds held in independent custody outside the country until milestone release; no payment through an account not cleared by the Compliance
- Independent A third-party procurement agent, published tender results and published contracts.
- Narrow first If the protocol clears, first packages are limited to domestic food production, cocoa rehabilitation and fisheries cold chain, with no public land grant accepted without competitive process.
If the protocol does not clear within two years, the envelope is released for reassignment.
Conditional-program financial structure
The program will use separate project companies, independent custody, milestone payments and documented currency and repatriation arrangements. If a conditional package cannot proceed, investment approval may preserve viable existing work and move eligible future functions and uncommitted allocations to qualified hosts.
Continental continuity
No conditional jurisdiction will be allowed to create an automatic cross-default for the remaining national programs. Guarantee arrangements, procurement commitments and shared-service dependencies will be reviewed for indirect exposure. Physical assets, contracts and paid-in capital cannot simply be reassigned across borders without legal rights, lender consent and applicable authorizations.
12. Governance and institutional responsibilities
| Body | Proposed responsibilities |
| Continental Supervisory Council | Country admission, continental strategy, major portfolio amendments and oversight; no unilateral government allocation power. |
| Independent Investment Committee | Project approvals, financing, disbursement gates, exposure limits and substitutions; documented conflict recusals. |
| Country Governance and Risk Committee | Country scoring, warning notices, corrective plans and suspension recommendations. |
| Technical Secretariat | Feasibility, biological validation, engineering, resource capacity and independent milestone verification. |
| Audit and Compliance Office | Financial controls, procurement integrity, beneficial ownership, sanctions and integrity screening and safeguard oversight. |
| National Steering Committee (one per country) | Government coordination, local implementation, public obligations and national milestones. |
| Country Program Management Office (one per country) | Project pipeline, schedules, procurement, finance coordination, reporting and operator performance. |
The Council may invite the African Union Commission, the AfCFTA Secretariat and regional economic communities to observe. Observer status is a courtesy to be requested; none of these bodies is represented as a participant or endorser.
Sponsor and master developer
The definitive proposal will identify the legal entity behind BioAfrica 1.4T, its ownership, registration, management, capitalization and verified delivery credentials. A brand is not a contracting party. Appointment as master developer must follow applicable law, procurement and foreign-investment rules, and a negotiated performance mandate in each country. Any exclusivity must be restricted to the defined program, measurable milestones and a specified term, with termination and cure provisions.
Government responsibilities and reserved authority
Governments will identify authorized agencies, provide reliable public data, coordinate lawful permitting, clarify incentives and tariffs, facilitate verified site access and document approved infrastructure support. They retain legislative, taxation, regulatory, judicial and public-security powers. Participation does not transfer sovereignty, confer blanket tax exemptions, override foreign-ownership or local-content rules, displace customary authorities or grant automatic rights to public or communal land.
Procurement and compensation
Contractors and technology partners will be prequalified, competitively evaluated where required, and contracted against acceptance criteria, delivery milestones, warranties and suitable security. Sole-source selections require documented justification and independent approval. Development fees, management fees, reimbursements and equity interests must be separately negotiated, benchmarked, capped where appropriate and disclosed before funding. Related-party appointments require recusal and independent review.
Financial controls
Project accounts will use approved custody, dual authorization, supplier verification and independent draw certification. Country and project audits will reconcile spending, commitments, liabilities and assets. Continental reporting will show each national exposure separately; consolidated presentation will not eliminate legal separation or conceal guarantees.
13. Country scoring, substitution and capital rules
Country ratings will use a 100-point framework applied identically to all fourteen countries: political stability 15; rule of law 15; investment protection and capital mobility 12; execution capacity 10; infrastructure 10; utilities 8; land and water 8; markets 6; workforce
5; environmental and social readiness 5; integrity 4; strategic fit 2. Rate each factor from 1 to 5 and calculate the weighted total as weight × (rating − 1) / 4, summed across factors.
Scores of 80–100 support preferred status; 70–79 standard approval; 60–69 conditional participation; 50–59 pilot-only treatment; below 50 no new investment. A legal prohibition or unacceptable safeguard risk overrides any numerical score. No scores are assigned in this proposal; the first scoring round follows the 180-day preparation review.
External indicators feeding the first scoring round
The two published indices below inform the political-stability and integrity factors. They are inputs, not scores, and they rank the fourteen countries very differently. Sources: 2026 Global Peace Index and 2025 Corruption Perceptions Index.
| Country | Peace rank, of 163 | Corruption-perception rank, of 182 |
| Mauritius | 18 | 61 |
| Equatorial Guinea | 38 | 172 |
| Botswana | 50 | 41 |
| The Gambia | 56 | 99 |
| Madagascar | 59 | 148 |
| Namibia | 63 | 65 |
| Morocco | 65 | 91 |
| Sierra Leone | 74 | 109 |
| Senegal | 75 | 65 |
| Ghana | 76 | 76 |
| Zambia | 82 | 99 |
| South Africa | 123 | 81 |
| Kenya | 132 | 130 |
| Country | Peace rank, of 163 | Corruption-perception rank, of 182 |
| Nigeria | 142 | 142 |
Triggers and responses
| Trigger | Response | Normal corrective window |
| Monitoring | Enhanced reporting, review and corrective plan. | 90–180 days |
| Capital hold | Pause new draws or commitments as authorized; protect viable operations. | 60–120 days |
| Partial substitution | Move selected future functions while retaining viable participation. | Up to 90 days |
| Full substitution | Stop new commitments; preserve, transfer or exit existing assets. | Immediate to 60 days |
Immediate action may be required for prohibited transactions, fraud, threats to personnel or serious environmental harm. An unconstitutional change of government or an African Union suspension triggers an automatic capital hold pending review. Notice, cure and termination must follow definitive contracts where lawful and practicable.
Replacement qualification
A replacement host normally needs a general score of at least 65 and a role score of at least 75. Role weights are functional capability 25; speed 15; sites and resources 15; infrastructure and markets 10; government support 10; legal protection 10; industry ecosystem 5; workforce 5; co-investment 3; supply-chain fit 2. Use the same normalized rating formula. A conditional country score does not authorize unrestricted scaling.
Reallocation waterfall and controls
First protect personnel, assets and the environment; then complete viable existing projects; transfer legally movable projects; reallocate to equivalent functions; consider other eligible continental uses; and cancel or return unusable commitments as required. Reserved envelopes are reassigned planning capacity, not transferred cash. Committed funds require financing-party consent and contract compliance.
For an initial reallocation, proposed limits are 35% of the eligible undisbursed amount to one host, 25% to one sector without renewed feasibility, 15% before construction- readiness confirmation, and 5% for transition and preparation. Pre-readiness spending excludes construction. Exceptions require a supermajority, independent risk opinion and any required investor consent. Re-entry does not recall allocations already reassigned.
Absorption review
Every five years the Investment Committee will compare each country’s qualified pipeline with its remaining envelope. Capacity with no qualified pipeline may be reassigned by the same waterfall, without any finding of fault against the country. This rule is expected to apply first to the smallest economies, where the envelope is many times annual GDP.
14. Safeguards, science and operating risk
Environmental and social management
Adopt the applicable host-country requirements and a lender-agreed environmental and social framework, using the eight IFC Performance Standards as a proposed benchmark for risk assessment and management. Project plans will cover labour, pollution, resource efficiency, community safety, land acquisition, biodiversity, Indigenous Peoples where relevant and cultural heritage. IFC is updating its framework, so applicable standards and financing conditions must be confirmed before approval.
Screen out projects that convert primary forest, wetlands or protected areas, damage mangroves, have unresolved critical habitat impacts, contested tenure, unmanageable displacement or unavailable sustainable water supply. Most land in the portfolio is held under customary or communal tenure: obtain meaningful community engagement and required consent from the households and authorities who actually hold the rights; protect pastoralist grazing routes and water points; maintain accessible grievances, documented responses and independent escalation. Budget mitigation, monitoring and livelihood restoration as project costs.
Projects that draw on shared rivers and lakes, including the Zambezi, Okavango, Orange, Niger, Volta, Senegal and Gambia rivers and Lake Victoria, must assess downstream effects on flows, fisheries and other users, and follow the notification and consultation procedures of the relevant basin organization. Coastal projects must protect mangroves and seagrass and avoid conversion for ponds.
Scientific and manufacturing controls
Biological laboratories and production plants require validated identity and purity methods, batch-release limits, stability data, contamination controls, staff training, appropriate containment and recall capability. Maintain lawful strain access, technology licenses and biosafety documentation. Livestock and aquaculture systems require species-specific biosecurity and professional oversight, including protocols for foot-and- mouth disease, small-ruminant plague, avian influenza and African swine fever.
Environmental products must be evaluated against actual influent and operating conditions.
| Material risk | Required mitigation |
| Financing and weak demand | Staged commitments, verified buyers, realistic affordability and downside underwriting. |
| Envelope larger than absorptive capacity | Draws tied to closed projects, five-year absorption review and reassignment of unused capacity. |
| Security and interrupted access | Site-level assessments, lawful protection, business continuity and stop-work authority. |
| Drought, flood, heat and cyclones | Water balances, resilient designs, appropriate siting, parametric insurance where available and emergency response. |
| Livestock and aquaculture disease | Biosecurity zoning, vaccination programmes, certified stock, surveillance and limited stocking density. |
| Technology underperformance | Independent trials, operator training, quality controls and limited initial exposure. |
| Currency, payment and transfer restrictions | Local-currency funding where feasible, reserves, contracted payment protections and legal review. |
| Public-debt and contingent-liability spillover | No sovereign guarantees by default; IMF and debt-sustainability review before any public contribution. |
| Material risk | Required mitigation |
| Elections and unconstitutional changes of government | No signings in the ninety days before a national election; automatic capital hold on a coup or African Union suspension. |
| Land tenure and community opposition | Title and customary-rights verification, documented consent, registered leases and grievance mechanisms. |
| Power and logistics failure | Independent power, contracted transport alternatives and storage buffers. |
| Construction and procurement | Independent engineer, contingency, suitable warranties and performance security. |
| Governance and corruption | Ownership disclosure, conflicts policy, competitive selection, independent custody, audits and protected reporting. |
| Loss of trade preferences | Base cases without AGOA after 2026; corridor-by-corridor AfCFTA verification; diversified buyers. |
| Sanctions and prohibited counterparties | List screening of owners, banks and logistics at each step, and stop rights in every contract. |
Insurance and liability
Assess construction, property, business interruption, product liability, environmental, worker, catastrophe and political-risk coverage, including from multilateral and African political-risk insurers. Insurance availability is not assumed. Non-recourse finance does not eliminate project risk, public contractual liabilities or sponsor obligations explicitly undertaken. Guarantees and public support must be authorized, priced, disclosed and capped in definitive agreements.
15. Workforce, markets and measurable impact
Local participation
Country programs will recruit local professionals, technicians and operators and develop qualified suppliers through apprenticeships, partnerships with national agricultural universities and research institutes, and transparent tender access. Young people and women farmers will have defined access to training, land-use contracts and supplier finance, with targets set after the skills and supplier baseline. Foreign specialists will support startup and transfer capability through documented training and succession plans.
Farmer and enterprise access
Establish field demonstrations, extension teams and service centres offering soil and water diagnostics, input advice, market information and collection services, with mobile- money payment where farmers prefer it. Input credit, equipment leasing and working- capital facilities require affordability review, clear repayment terms and borrower protections. Participation remains voluntary; growers may use independent advice and grievance channels.
Commercial market development
Before construction, validate demand by product, grade, season, price, packaging and destination. Secure credible distributors or offtakers where appropriate, while avoiding excessive reliance on one buyer. Domestic food-security projects must account for local purchasing power. Export models must include freight, certifications, border delays, spoilage and payment risk, and must name the trade regime relied on. Manufacturing capacity will scale to sales evidence and regulatory readiness.
| Metric | Measurement and approval basis |
| Capital mobilization | Binding commitments, closed finance and verified disbursement reported separately. |
| Employment and skills | Direct full-time-equivalent jobs, temporary jobs and training completions, by sex and age group; no double counting. |
| Metric | Measurement and approval basis |
| Production and farmer income | Marketable volumes, quality, post-harvest loss, farm margins and payment timing versus baseline. |
| Biological product performance | Validated batch counts, shelf life, trial results and customer outcomes. |
| Intra-African trade | Volumes and values sold across borders, by corridor and trade regime used. |
| Water and energy | Measured withdrawals, reuse quality and consumption per unit of output. |
| Environment and community | Waste treatment, residue burning avoided, land restored, safeguard compliance, grievances and livelihood restoration. |
| Commercial sustainability | Operating margins, liquidity, debt coverage, buyer concentration and arrears. |
Reporting and verification
Each Country Program Management Office will publish quarterly portfolio and country summaries with commercial confidentiality protected. Investors receive detailed finance, risk, milestones and safeguards reports; material incidents are notified promptly under contractual timelines. Independent annual audits and technical reviews will validate results. Targets must include a baseline, measurement method, owner and review date.
Changes require recorded approval.
Employment multipliers, national GDP effects, carbon benefits and fertilizer savings will not be advertised as achieved outcomes without transparent methods and supporting evidence. The program will report its contribution to the Kampala and Nairobi targets without claiming sole causation for national changes.
16. Launch decisions and definitive agreements
First-year funding request
The first year asks for US$2.7 billion, about 0.2% of the envelope. Every line needs its own funding commitment and package-level approval; conditional lines are released only as each protocol allows.
| Program | First-year budget, US$ million | Subtotal, US$ million |
| Launch: Morocco, Ghana | 500 each | 1,000 |
| Anchor: South Africa, Nigeria | 250 each | 500 |
| Anchor: Kenya, Zambia | 200 each | 400 |
| Core: Mauritius, Botswana, Namibia | 100 each | 300 |
| Core: The Gambia, Sierra Leone | 50 each | 100 |
| Conditional: Senegal | 150 | 150 |
| Conditional: Madagascar | 50, grant-funded only | 50 |
| Conditional: Equatorial Guinea | 25, review only | 25 |
| Continental governance, compliance and preparation facility | 175 | 175 |
| TOTAL | 2,700 |
First 180 days
| Timing | Required deliverables and accountable lead |
| Days 1–30 | Sponsor: verify legal entity, ownership and mandate. Governments: designate counterparts. Council: approve governance and funded preparation scope. |
| Days 31–60 | Country PMOs: establish project registries, site screening, stakeholder plans, legal reviews and baseline data rooms. |
| Days 61–90 | Technical Secretariat: shortlist viable clusters; commission feasibility and safeguard studies. Finance team: match asset classes to capital providers. |
| Timing | Required deliverables and accountable lead |
| Days 91–120 | PMOs: validate buyers and operators, resource supply, permits and cost estimates. Compliance Office: complete counterparty reviews and the Senegal, Madagascar and Equatorial Guinea protocol reviews. |
| Days 121–180 | Investment Committee: run the first country scoring round; approve qualified pilot packages and first project term sheets; close eligible finance; authorize only readiness-compliant draws. |
Agreement package
Implementation will require: a national cooperation and development framework; lawful master-developer appointment; country and project corporate documents; land leases, concessions or use rights; project-specific permits; environmental and social plans; financing and security agreements; construction and equipment contracts; technology licenses; operating and maintenance contracts; offtake arrangements; insurance; and audit and reporting mandates. Tax, public support, dispute resolution, change in law, termination and lender step-in rights require jurisdiction-specific negotiation.
Approval requested from governments
Endorse the program for feasibility and negotiations and appoint an authorized national steering group.
Authorize access to available public data and lawful site evaluation; coordinate the permitting process without pre-approving outcomes.
Agree transparent oversight, community protections and procurement principles; identify public contributions requiring separate approval.
Approval requested from sponsors and capital partners
Fund a defined preparation budget; approve management, independent oversight and conflict controls.
Review project opportunities through staged mandates; commit capital only against approved terms and conditions.
Support qualified local operators and suppliers and finance replicable projects once technical and commercial performance is established.
Scope of approval
Approval in principle establishes a path to preparation. It does not constitute financial close, a securities offering, a government procurement award, a land conveyance or an automatic sovereign obligation. The definitive legal entities, budgets, funding, authorities and terms must be settled before binding execution.
17. Reference terms and supporting material
Proposed commercial terms for negotiation
| Term | Proposal |
| Program size and horizon | Up to US$1.4 trillion across fourteen national envelopes; reference horizon 25–30 years, with accelerated eligible deployment. |
| Initial priority | Morocco and Ghana first; South Africa, Nigeria, Kenya and Zambia as anchor economies under stated conditions; Mauritius, Botswana, Namibia, The Gambia and Sierra Leone admitted by readiness; Senegal, Madagascar and Equatorial Guinea subject to their country protocols. |
| Preparation mandate | A defined, funded scope and milestone schedule; initial 180-day review followed by negotiated renewal. |
| Master-developer term | Country-specific, performance-based and subject to lawful procurement; no blanket national monopoly. |
| Project ownership | Negotiated per project within national foreign- ownership and local-content rules; public and communal land remain subject to lawful title, consent and concession arrangements. |
| Term | Proposal |
| Financing | Non-recourse or limited-recourse where feasible; separately disclosed public commitments and guarantees; no sovereign borrowing by default. |
| Integrity and sanctions compliance | Counterparty clearance, representations and termination rights in every contract; no performance without current authorization. |
| Fees and carried interests | Negotiated, independently reviewed and disclosed; no implied percentage or automatic entitlement. |
| Capital releases | Approved budget, financial close, conditions precedent and independently verified milestones. |
| Unused capacity | Reassigned at five-year absorption reviews under the section 13 waterfall. |
| Termination and disputes | Defined breach, notice, cure, asset protection, compensation rules and enforceable dispute process negotiated with counsel. |
Required investment data room
The sponsor will provide entity and ownership records, management credentials, governance charter, capital evidence and conflicts disclosures. Each country file will contain authority documents, legal and tax analysis, integrity and sanctions analysis where relevant, security assessment, debt-sustainability review, country scoring and site inventory. Each project file will contain resource studies, title and customary-rights verification, engineering, permits, safeguards, buyer and operator evidence, budgets, financial models, financing terms and implementation risks.
External reference framework
- Ecofin Agency, Africa rankings from the 2026 Global Peace Index. Index released 9 June 2026; source of every peace rank used
- Ecofin Agency, Africa rankings from the 2025 Corruption Perceptions Index. Published 11 February 2026; 182 countries
- Wikipedia, List ofAfrican countries by GDP (nominal). IMF 2026 estimates; the IMF database itself should be checked before these figures are relied
- tralac, Status ofAfCFTA ratification. 50 ratifications as of 4 September
- Welthungerhilfe, From Malabo to Kampala. Kampala CAADP Declaration targets for
- Rural 21, African countries decide to tackle soil health challenges. Nairobi Declaration targets for
- International Finance Corporation, Performance Standards. Proposed benchmark; the 2012 standards are under
- Baker McKenzie, AGOA’s one-year extension. Extension to 31 December
- Hespress, Morocco’s share of phosphate reserves, and AgriFocus Africa, Generation Green mid-term review. The reserve share is a secondary-source figure dated May
- Ghana News Agency, Ghana completes IMF programme. July
- Engineering News, Reform tracker on South African energy and logistics, and Africanews, Foot-and-mouth vaccination campaign.
- Nairametrics, Food insecurity projections for Nigeria, and AllAfrica, Nigeria’s 2027 election timetable.
- Ecofin Agency, Kenya’s IMF talks and public debt. Position at May 2026; later developments not
- TimesLIVE, Zambia’s election and IMF position. August
- Mining Weekly, Moody’s downgrade of Botswana, and The Namibian, 2024 Ibrahim Index ofAfrican Governance.
- The Point, The Gambia’s election date; Daba Finance, Senegal’s IMF agreement and debt; ISS Africa, Madagascar’s transition.
Reference pages reviewed 8 October 2026. Most are news reports of the underlying indices and official statements; primary sources should be confirmed during preparation. Statements about crops, regions, land tenure and river basins that carry no link reflect general knowledge and have not been verified against a source. Country-specific laws, procurement, financing eligibility, registrations and permits will be verified during preparation. No reference institution is represented as a participant or financier.